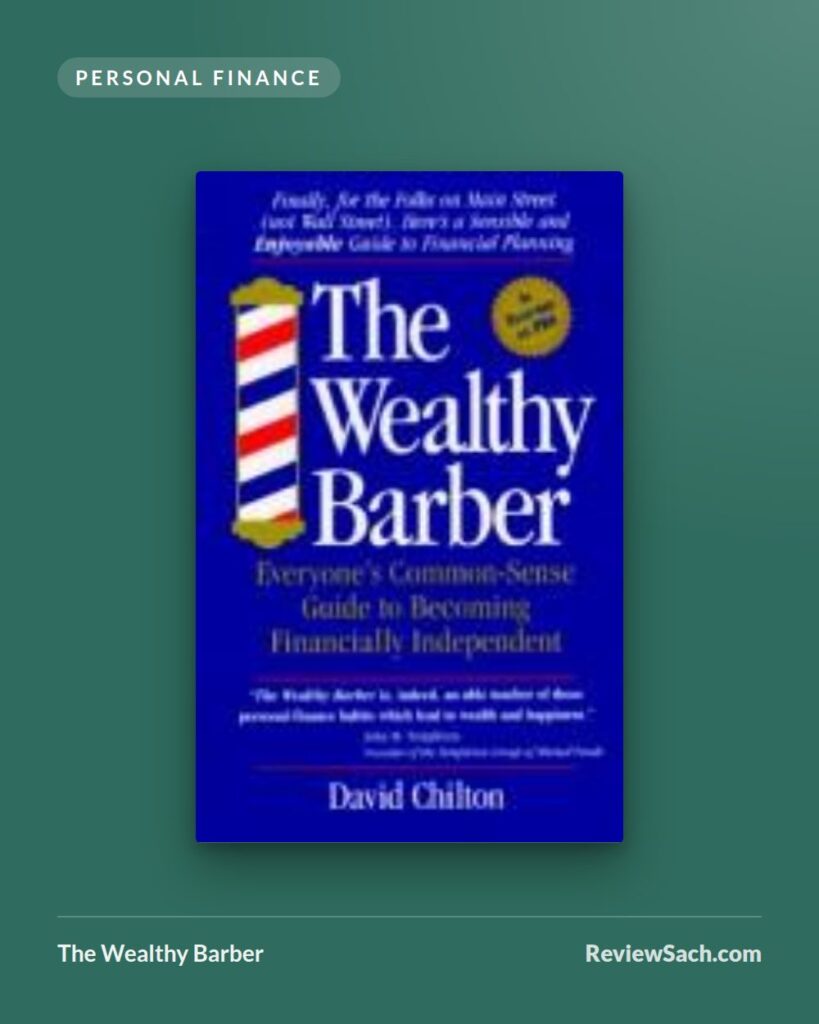
Author: David Chilton · Published: 1989 · Genre: Personal Finance, Fiction
The Wealthy Barber teaches the basics of personal finance through a gentle story about a small-town barber who dispenses money advice. Its core message, save 10% of everything you earn, is timeless, and it remains a pleasant first book for beginners. But the 1989 original’s numbers and investment advice are badly dated, so read it for the habits, not the specifics.
What it’s about
David Chilton, a Canadian financial writer, set the book in Sarnia, Ontario. The narrator, Dave, and his companions Cathy and Tom meet Roy, a barber who has become quietly rich, for monthly lessons in the barbershop. Roy has no big salary, inheritance or insider knowledge. He simply saved a tenth of his income for decades, starting young, and let compound growth do the work.
Each lesson tackles one topic, and Roy expects his students to act on it before the next haircut. He covers paying yourself first through automatic savings, making a will, carrying enough life insurance if people depend on you, owning your home, using tax-sheltered retirement plans (RRSPs in the Canadian original) and investing regularly through dollar-cost averaging.
The book became a huge bestseller in Canada and has been revised over the years. Don’t confuse it with The Wealthy Barber Returns (2011), a separate book of short essays in Chilton’s own voice that focuses on spending and behaviour.
What works
- The 10% rule. Saving a fixed slice of income before spending anything is simple, memorable and effective. Countless later books repeat it, often less clearly.
- Story format. Wrapping lessons in conversation makes wills and insurance far less dull. Readers who would never open a finance textbook often finish this in a weekend.
- Priorities. Roy gets people to handle unglamorous essentials, such as a will and adequate insurance, before worrying about which investments to buy.
- Compounding made visible. Roy’s own life is the proof of concept. A modest income, an early start and decades of steady saving turn into real wealth, which is more persuasive than any chart.
- Tone. It is warm, funny in places and never talks down to readers. Roy is patient, and his modest lifestyle makes the point that wealth comes from habits rather than income.
What doesn’t
Age is the problem. The original assumed investment returns that look optimistic today, and its investing advice relied on actively managed mutual funds, chosen by researching good fund managers. Canadian funds of that era often carried high fees, and decades of evidence since then favour low-cost index funds. Chilton himself has changed his tune. His rewritten 2025 edition has Roy championing low-cost index funds and warning about the damage fees do over time.
It also assumes a fairly comfortable reader: someone with a steady job, manageable debt and a little spare cash each month. People dealing with heavy debt, low pay or irregular income get little direct help, which limits its value as a true starting point for everyone.
The fictional frame is also thin. The characters exist mainly to ask the right questions, and the dialogue can feel like a lecture in costume. Much of the tax detail is Canadian, so other readers must translate RRSPs and local rules into their own equivalents.
The biggest risk is picking up an old copy and following it literally. The habits hold up; the specific products, interest rates and contribution rules do not. Anyone acting on it should check current rules and fees first.
Who should read it
Complete beginners, especially young Canadians, who need a friendly nudge to start saving. Read the newest edition if you can, and pair it with a modern guide to index investing.
Rating: 3/5
Image credits — Cover image via Open Library. Cover design © the publisher, shown for review purposes.
